Government payroll modernization is a compliance program, not only a software replacement project. A 2027 modernization program should establish a controlled operating model across payroll calculation, tax reporting, time and leave, security, and ongoing support.
Government payroll modernization is a compliance program, not only a software replacement project.
Public-sector employers must manage payroll rules across federal, state, and local jurisdictions. They must also support public retirement systems, collective bargaining provisions, timekeeping, leave, funding dimensions, audits, and employee self-service.
A 2027 modernization program should establish a controlled operating model across five areas:
- Payroll calculation
- Tax and regulatory reporting
- Time and leave administration
- Security and auditability
- Ongoing production support
Workday, UKG, and Microsoft Dynamics can serve as technology examples. None should be selected without a documented fit assessment.
Public-Sector Payroll Requirements
Government payroll differs from private-sector payroll in several ways.
Public employers may manage:
- Multiple agencies and business units
- Federal, state, county, municipal, or special-district employees
- Elected and appointed officials
- Seasonal and temporary workers
- Public safety schedules
- Union contracts
- Step-based pay plans
- Grants, funds, programs, and projects
- Public retirement systems
- Special Social Security coverage rules
- Complex leave accruals
- Government-specific reporting requirements
The employer remains responsible for accurate payroll administration even when processing is outsourced. The IRS states that an employer generally remains responsible for employment tax duties when using a third-party payer or payroll service provider.
Modernization must therefore address governance and accountability. The system must show who entered, approved, changed, calculated, and released each payroll result.
Federal, State, and Local Distinctions
Federal government payroll requirements are not identical to state and local requirements.
Federal employees may have different Social Security and Medicare treatment based on hire date, employment category, and applicable federal rules.
State and local government employers generally must withhold federal income tax. Social Security and Medicare treatment may depend on whether an employee is covered by a public retirement system, mandatory coverage rules, or a Section 218 agreement. State and local governments are generally exempt from FUTA tax, but the payroll team must validate each applicable rule.
State and local employers must also account for state and local income tax, paid-leave programs, wage notices, unemployment rules, garnishments, and reporting requirements.
A modern system should store the rule basis for each employee and position. Payroll staff should not rely on undocumented spreadsheets or individual memory.
Section 218 Considerations
Section 218 agreements establish Social Security coverage for employees of states and political subdivisions. The agreement applies through the state. Coverage can vary by position, retirement system, employee group, or governmental entity.
A modernization project should identify:
- The state's Section 218 agreement
- Modifications and amendments
- Covered and excluded positions
- Optional coverage groups
- Retirement-system participation
- Medicare-only coverage
- Employment status changes
- Intergovernmental transfers
- Record retention requirements
The payroll design should connect Section 218 status to the employee, position, and employing entity. Manual overrides should require approval and produce an audit record.
Configuration should be tested using representative scenarios. Test cases should include new hires, rehires, transfers, employees entering or leaving a retirement system, and employees moving between covered and non-covered positions.
W-2 and Form 941 Responsibilities
Payroll modernization must support the complete reporting cycle.
Employers generally must:
- Withhold applicable federal income tax
- Withhold employee Social Security and Medicare taxes
- Pay the employer share when required
- Deposit employment taxes
- File Form 941 when applicable
- Furnish Forms W-2
- File Forms W-2 and W-3 with the Social Security Administration
- Reconcile quarterly payroll reporting with annual wage reporting
- Correct errors using the appropriate amended forms
Form 941 reports federal income tax withheld and Social Security and Medicare taxes for the quarter. Form W-2 reports annual employee wages and withholding.
The system should support reconciliations between:
- Payroll registers
- General ledger postings
- Tax deposits
- Form 941 data
- W-2 data
- Benefit and retirement deductions
- Third-party payment files
Differences may be valid. They must still be explainable. A controlled reconciliation process should document the reason for each difference.
Timekeeping and Leave Integration
Payroll accuracy depends on upstream data.
Timekeeping must capture the data required by the pay rules. This can include:
- Regular hours
- Overtime
- Shift differentials
- On-call time
- Emergency response time
- Holiday work
- Premium pay
- Compensatory time
- Union-specific rules
- Multiple assignments
- Supervisor approvals
Leave administration must support accruals, balances, eligibility, carryover rules, payouts, and leave types. Payroll should receive approved leave data through a controlled integration.
A disconnected timekeeping system increases reconciliation effort. It can also create delayed corrections and inconsistent employee balances.
The target architecture should define which system owns each data element. It should also define validation, error handling, retry procedures, and ownership for failed integrations.
Security and Auditability
Payroll contains personally identifiable information, tax data, bank information, compensation details, and benefits data.
Security design should include:
- Role-based access
- Segregation of duties
- Multi-factor authentication
- Encryption in transit and at rest
- Privileged access controls
- Approval workflows
- Logging of configuration changes
- Logging of payroll adjustments
- Monitoring of integration activity
- Periodic access reviews
- Retention and disposal procedures
Access should reflect job responsibilities. A timekeeper should not have unrestricted payroll administration rights. A payroll processor should not be able to approve their own high-risk changes without independent review.
Auditability must extend beyond the payroll result. It should include the source transaction, approval, configuration version, calculation result, payment file, and correction history.
Platform Fit Assessment
Workday, UKG, and Microsoft Dynamics can support different portions of a modernization program. The correct choice depends on the employer's requirements.
Workday
Vendor-provided Workday materials describe public-sector payroll capabilities that include multiple pay groups, payment calendars, contract pay, payroll audits, self-service, reporting, and integration options.
These claims should be validated through demonstrations, reference checks, security review, and scenario-based testing. Agencies should confirm support for their Section 218 structure, tax requirements, labor rules, pay groups, leave policies, and financial dimensions.
UKG
UKG provides public-sector workforce management and government-focused product resources. UKG may be relevant where scheduling, timekeeping, workforce management, and public-sector operational rules are central requirements.
The evaluation should confirm payroll scope, tax services, integrations, security controls, reporting, implementation responsibilities, and support coverage. Product fit should be tested against actual agency rules.
Microsoft Dynamics
Microsoft Dynamics may be considered where the organization already uses Microsoft business applications or requires integration with finance, procurement, data, and workflow services.
A Dynamics-based design may require additional payroll components or integrations. The agency should define the system of record for payroll, time, leave, employee data, tax calculations, and financial posting before selecting the architecture.
BTG can support management consulting, requirements analysis, vendor evaluation, implementation governance, and IT managed services for testing, documentation, and production support.
Five-Phase Modernization Roadmap
Phase 1: Assess
Document the current environment.
Review:
- Payroll processes
- Timekeeping and leave rules
- Section 218 documentation
- Tax reporting
- Interfaces
- Security roles
- Manual workarounds
- Data quality
- Audit findings
- Employee service issues
Create a requirements inventory. Separate legal requirements from preferences.
Phase 2: Design
Define the future operating model.
Establish:
- System ownership
- Payroll calendars
- Pay groups
- Data structures
- Approval workflows
- Security roles
- Integration patterns
- Reporting requirements
- Reconciliation controls
- Support responsibilities
The design should include federal, state, and local distinctions.
Phase 3: Prepare
Prepare data, people, and controls.
Activities include:
- Data cleansing
- Position and employee mapping
- Rule inventory
- Interface specifications
- Security design
- Test strategy
- Training plan
- Cutover plan
- Communications plan
- Issue management process
Preparation should begin before configuration is complete.
Phase 4: Implement and Test
Configure the selected solution and execute formal testing.
Testing should include:
- Unit testing
- System testing
- Integration testing
- Security testing
- User acceptance testing
- Payroll calculation testing
- Time and leave testing
- W-2 and Form 941 reconciliation
- Parallel payroll processing
- Payment file validation
- Cutover rehearsal
Parallel testing should cover multiple pay periods. Results should be compared by employee, earning, deduction, tax, leave balance, and accounting dimension.
Defects should be classified by severity. Go-live approval should require documented resolution or acceptance of remaining risks.
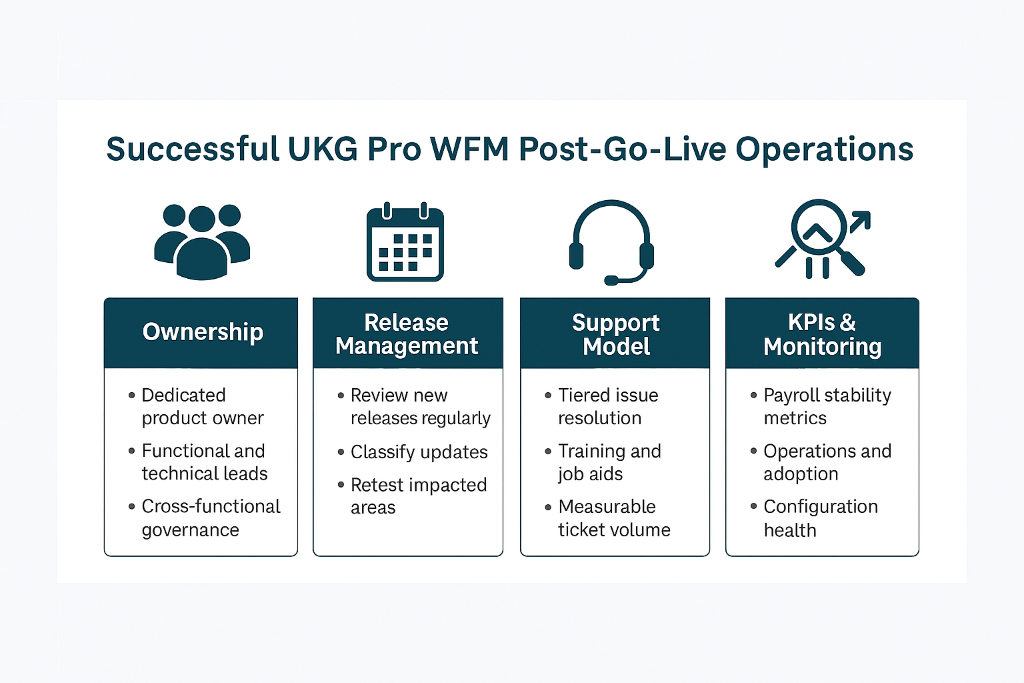
Phase 5: Operate and Optimize
Go-live is the beginning of the operating model.
Post-production activities should include:
- Payroll monitoring
- Incident management
- Root-cause analysis
- Regulatory updates
- Access reviews
- Regression testing
- Release management
- Knowledge management
- Employee support
- Quarterly reconciliation
- Annual year-end preparation
A managed support model can help maintain system knowledge after implementation. BTG provides production support, testing, documentation, and staff augmentation through its IT Managed Services practice.
Employee Self-Service and Change Management
Employee self-service should provide controlled access to:
- Pay statements
- Tax forms
- Payment elections
- Tax withholding elections
- Time entries
- Leave balances
- Benefit deductions
- Personal information
Self-service access must include identity verification, role controls, audit logging, and support procedures.
Change management should begin during assessment. Employees and managers need clear information about:
- What is changing
- When it is changing
- Which actions are required
- Where to obtain help
- How corrections will be handled
- How payroll questions will be escalated
Training should be role-specific. Payroll staff, managers, timekeepers, HR users, finance users, and employees have different responsibilities.
Conclusion
Government payroll modernization in 2027 should be managed as a controlled transformation of people, process, data, and technology.
The target state is not simply a new payroll application. It is an auditable operating model that supports Section 218 requirements, tax reporting, timekeeping, leave, security, integrations, employee service, testing, and ongoing support.
Select the platform after documenting the requirements. Test public-sector scenarios before approving production. Build the support model before cutover.
Sources
- IRS Publication 963: Federal-State Reference Guide
- IRS Publication 15: Employer's Tax Guide
- Workday Payroll for the Public Sector Datasheet
- UKG Public Sector Solutions
- UKG GovTA
- Workday State and Local Government Solutions